Eternal SBI Credit Card Review: 10% Off Zomato and District, But What Will You Actually Save?
Eternal SBI offers up to 10% off Zomato, Blinkit and District. We break down the ₹499 fee, cashback caps and what you can save on everyday spending.
 Gajender Yadav
11 min read
Interested in the Eternal SBI Credit Card? Reserve your card through the Blinkit, Zomato or District app.
Benefits verified: 15 October 2026
It is Friday evening. Work has run late, the refrigerator needs restocking, and cooking can wait until tomorrow.
You order dinner on Zomato. A few minutes later, you open Blinkit for milk, fruit and the things you forgot to buy on Sunday. Later, there is an Uber ride to meet friends.
On Saturday, you open District to plan an evening out. Across the month, there might also be a home-service appointment through Urban Company or a pharmacy purchase through Apollo. When travel comes around, ixigo enters the picture.
These purchases serve different needs, but they can sit inside the same card strategy: Zomato × Blinkit × District for everyday discounts, with selected partners extending the value beyond those three apps.
That is where the Eternal SBI Credit Card fits into the conversation. With a ₹499 + GST annual fee, it puts discounts on Zomato, Blinkit and District, then adds cashback at selected partners.
For someone who already uses these platforms, the appeal is easy to see. The harder question is how much stays in your pocket after caps, exclusions, transaction rounding and the card fee.
The best reason to hold Eternal SBI is a month of ordinary purchases that costs a little less, without changing what you buy.
Let us follow the money from one evening to a full year.
Calculations assume eligible purchases, sufficient cap and no extra transaction restrictions. Amounts for instant discounts mean qualifying purchase value, which may differ from the final cart total.
One Friday Evening: ₹2,400 of Purchases, ₹160 of Benefits
Imagine the eligible dinner amount is ₹800, groceries cost ₹1,200 and the cab ride is ₹400.
| Purchase | Calculation | Benefit | When you receive it |
|---|---|---|---|
| Zomato dinner | ₹800 × 10% | ₹80 | Instant discount |
| Blinkit groceries | ₹1,200 × 5% | ₹60 | Instant discount |
| Uber ride | ₹400 × 5% | ₹20 | Statement cashback |
| Total | ₹2,400 purchase value | ₹160 | ₹140 now + ₹20 later |
The initial card charges total ₹2,260 after ₹140 in checkout discounts. Once ₹20 cashback is credited, the effective cost is ₹2,240.
That is a 6.67% benefit on the original ₹2,400, before allocating any annual fee. The cab cashback still needs to qualify under the partner’s merchant identifiers.
A useful beginning. Now see whether the same logic survives a whole month.
Quick Overview: What the Card Actually Offers
| Feature | Eternal SBI Credit Card |
|---|---|
| First-year annual fee | ₹499 + GST |
| Renewal fee | ₹499 + GST from the second year |
| Renewal-fee waiver | On ₹2 lakh annual spending; qualifying-spend rules apply |
| Zomato | 10% instant discount |
| Blinkit | 5% on other categories; 10% on beauty and electronics |
| District | 10% instant discount |
| Shared Eternal cap | ₹2,000 per calendar month |
| Uber, Urban Company and Apollo | 5% eligible statement cashback |
| ixigo flights and hotels | 4% instant discount with IXIGOSBI + 1% cashback |
| Preferred-partner cashback cap | ₹1,000 per statement cycle |
| Other eligible purchases | 1% cashback, capped at ₹500 per billing cycle |
| Cashback calculation | Completed ₹100 blocks per transaction; no cashback below ₹100 |
| Cashback credit | Within two working days of statement generation |
| Zomato Gold | Complimentary six-month membership on activation |
| District movies | BOGO once per month; up to ₹200 off the second ticket |
| Networks | Mastercard and RuPay; eligible merchant UPI on RuPay earns 1% |
| Fuel surcharge waiver | 1% on ₹500–₹4,000 transactions; up to ₹200 per statement cycle |
| Add-on annual fee | Nil |
A ₹20,000 Month: Where the Card Starts Earning Its Place
Dinner on Zomato. Groceries from Blinkit. An evening booked through District. The occasional ride, home-service appointment and pharmacy order fill out the month.
Here is an illustrative ₹20,000 budget that gives those partners a clear role. Every purchase is assumed to be something the household already intended to make.
| Monthly purchases | Eligible value | Benefit rate | Savings |
|---|---|---|---|
| Zomato | ₹4,000 | 10% | ₹400 instant discount |
| Blinkit groceries | ₹6,000 | 5% | ₹300 instant discount |
| Uber | ₹1,000 | 5% | ₹50 cashback |
| Urban Company | ₹600 | 5% | ₹30 cashback |
| Apollo | ₹400 | 5% | ₹20 cashback |
| District | ₹2,000 | 10% | ₹200 instant discount |
| Other eligible purchases | ₹6,000 | 1% | ₹60 cashback |
| Total | ₹20,000 | 5.3% blended benefit | ₹1,060 |
₹900 stays in the wallet at checkout across Zomato, Blinkit and District. ₹160 comes back through the card account. The final card charges are ₹19,100; after the cashback, the effective purchase cost is ₹18,940. The District row counts only the 10% instant discount, with no movie BOGO stacking assumed.
For the cashback rows, assume individual transactions are in completed ₹100 blocks. If the ₹2,000 combined partner spending is split into amounts that lose value to rounding, or payments below ₹100, actual cashback can be lower.
From One Month to a Year
For the fee calculations in this article, assume 18% GST. That makes a ₹499 fee ₹588.82 in total. Use the tax actually charged on your account.
| Annual calculation | Amount |
|---|---|
| Eligible purchase value: ₹20,000 × 12 | ₹2,40,000 |
| Instant discounts: ₹900 × 12 | ₹10,800 |
| Statement cashback: ₹160 × 12 | ₹1,920 |
| Gross annual benefit | ₹12,720 |
| First-year fee, assuming 18% GST | −₹588.82 |
| Benefit after first-year fee | ₹12,131.18 |
| Net benefit ÷ ₹2,40,000 purchase value | About 5.05% |
Gold, movie offers and fuel benefits are assigned no value here. The annual illustration assumes the same eligible pattern for 12 months and unchanged benefits.
The ₹2.4 lakh is purchase value before instant discounts, not the issuer’s renewal-waiver spend count. Check what SBI Card includes before assuming the fee is waived in year two.
A Smaller Budget: You Do Not Need to Chase the Cap
Perhaps your month is quieter: ₹2,000 of Zomato orders and ₹3,000 of Blinkit groceries. No attempt to move the entire household budget onto one card.
| Purchase | Monthly benefit | If repeated for 12 months |
|---|---|---|
| Zomato: ₹2,000 × 10% | ₹200 | ₹2,400 |
| Blinkit groceries: ₹3,000 × 5% | ₹150 | ₹1,800 |
| Total on ₹5,000 monthly purchases | ₹350 | ₹4,200 |
| First-year fee with assumed 18% GST | — | −₹588.82 |
| Annual benefit after fee | — | ₹3,611.18 |
That is a 7% gross benefit on these purchases, or about 6.02% after allocating the illustrated first-year fee across ₹60,000 of annual purchases.
But ₹3,611.18 is not automatically the improvement from adding a new card. Your existing card may already earn something on the same orders.
The Existing Card in Your Wallet Changes the Answer
Suppose, purely as a comparison, your existing card earns 5% on both those platforms, with full eligibility, sufficient cap and no additional fee to incur.
| Route for the same ₹5,000 monthly purchases | Monthly benefit | Annual benefit |
|---|---|---|
| Eternal SBI: 10% Zomato + 5% groceries | ₹350 | ₹4,200 |
| Hypothetical existing card: 5% on both | ₹250 | ₹3,000 |
| Extra benefit before Eternal’s fee | ₹100 | ₹1,200 |
| Less Eternal first-year fee, assumed GST included | — | −₹588.82 |
| Additional annual value from adding Eternal | — | ₹611.18 |
The same purchases that produce ₹4,200 in gross benefits create just ₹611.18 of additional first-year value in this comparison. That may still be worthwhile. It deserves a different decision from a headline promising thousands of extra rupees.
Sometimes the Best Strategy Uses Two Cards
Return to the ₹20,000 monthly budget. Suppose you already hold a card earning a hypothetical flat 2% on every purchase in that example. Keep its existing fee outside this incremental comparison.
| How you pay | Monthly benefit | What changes |
|---|---|---|
| Existing 2% card for all ₹20,000 | ₹400 | Baseline |
| Eternal for all eligible purchases in the example | ₹1,060 | ₹660 more before Eternal’s fee |
| Eternal for Zomato, Blinkit, District, Uber, Urban Company and Apollo; existing 2% card for the other ₹6,000 | ₹1,120 | ₹900 discounts + ₹100 partner cashback + ₹120 elsewhere |
The last route improves benefits by ₹720 a month over the baseline. Across 12 repeated months, that is ₹8,640, or ₹8,051.18 after Eternal’s illustrated ₹588.82 first-year fee.
The useful job for Eternal is clear: pay for the categories where its benefit is stronger. Let another card handle purchases where it earns more.
Zomato × Blinkit × District: Three Apps, One ₹2,000 Allowance
Zomato, Blinkit and District share a ₹2,000 instant-discount allowance per calendar month. Spending on one app reduces what is available on the others.
| Sequence of eligible purchases | Calculated discount | Shared cap remaining |
|---|---|---|
| ₹8,000 Zomato at 10% | ₹800 | ₹1,200 |
| ₹10,000 Blinkit groceries at 5% | ₹500 | ₹700 |
| ₹7,000 District at 10% | ₹700 | ₹0 |
| Another ₹1,000 eligible 10% purchase in that calendar month | ₹0 from this capped benefit | ₹0 |
The first ₹25,000 produces ₹2,000 of discounts: an 8% blended benefit. After the next ₹1,000, total discounts remain ₹2,000 and the blended benefit falls to about 7.69%.
At 10% throughout, ₹20,000 of eligible purchases reaches the cap. At 5% throughout, it takes ₹40,000. Mixed baskets on Blinkit require a checkout check because item-level treatment can matter.
Beyond Zomato × Blinkit × District: Uber, Urban Company, Apollo and ixigo
| Partner | Benefit | Practical use |
|---|---|---|
| Uber | 5% cashback | Eligible rides |
| Urban Company | 5% cashback | Eligible home and beauty services |
| Apollo | 5% cashback | Eligible healthcare and pharmacy purchases |
| ixigo flights and hotels | 4% instant discount with IXIGOSBI + 1% cashback | Apply the coupon; check booking conditions and final card charge |
The partner list gives the card a role between food orders and weekends out: a ride with Uber, a planned home service with Urban Company, an eligible healthcare or pharmacy purchase with Apollo, and a flight or hotel booking on ixigo when you need to travel.
The preferred-partner document caps cashback at ₹1,000 per statement cycle. ₹20,000 of eligible purchases earning 5% cashback in ₹100 blocks reaches that ceiling.
ixigo needs special attention. Its offer splits into a checkout discount and statement cashback. Do not describe it as 5% statement cashback or automatically add the two percentages on the original booking value: the cashback base and offer limits matter.
Qualification depends on eligible merchant identifiers supplied to SBI Card. A familiar merchant name on the transaction is not sufficient by itself.
The Small-Transaction Catch: Why 1% Can Become Less Than 1%
The RuPay variant earns 1% on eligible merchant UPI payments, but small transactions have a catch. The booklet requires completed ₹100 blocks per transaction and gives no cashback below ₹100.
| Eligible transaction | Rate | Calculation | Cashback | Effective return |
|---|---|---|---|---|
| ₹99 | 1% | Below the minimum | ₹0 | 0% |
| ₹199 | 1% | ₹100 × 1% | ₹1 | About 0.50% |
| ₹2,999 | 1% | ₹2,900 × 1% | ₹29 | About 0.97% |
| ₹2,999 at a qualifying 5% partner | 5% | ₹2,900 × 5% | ₹145 | About 4.83% |
This is why ₹50,000 of total payments does not always generate the full ₹500 base-cashback cap. The total of each transaction’s qualifying blocks decides the outcome.
The card is available on Mastercard and RuPay. The merchant UPI benefit applies to the RuPay route and remains subject to base-cashback eligibility and caps.
What the ₹42,000 Illustration Really Requires
There is a larger number in the conversation: ₹3,500 from the three core buckets, annualised to ₹42,000. Here is the spending behind it.
| Core bucket | Full allowance | Illustrative qualifying purchases |
|---|---|---|
| Eternal instant discounts | ₹2,000 per calendar month | ₹20,000 entirely in 10% categories |
| Preferred-partner cashback | ₹1,000 per statement cycle | ₹20,000 at eligible 5% cashback partners |
| Base cashback | ₹500 per billing cycle | ₹50,000 of other eligible purchases in ₹100 blocks |
| Combined illustration | ₹3,500 | ₹90,000 purchase value |
Using 12 full calendar-month discount allowances and 12 full cashback-cycle allowances yields ₹42,000 gross. The illustrated annual purchase value is ₹10.8 lakh. Subtracting a first-year fee of ₹588.82 leaves ₹41,411.18 under the same assumptions.
That is about 3.83% of the ₹10.8 lakh purchase value after the illustrated fee. A larger rupee saving does not necessarily mean a higher percentage return.
These periods do not automatically line up. The booklet’s initial-cycle example runs from a first purchase on 19 March to 22 April for a 22nd-of-month billing date. Treat ₹42,000 as an annualised illustration, rather than a guaranteed first-year result.
Gold, movies, fuel waivers and ixigo’s separate instant-discount component are excluded. This is the sum of three core allowances, not an absolute ceiling on every possible card benefit.
The Fee: Small Enough to Recover, Worth Calculating Properly
The first-year fee is ₹499 + GST; renewal is ₹499 + GST from the second year. At the assumed 18% GST, the cost is ₹588.82.
| Benefit route | Approximate qualifying purchases to recover ₹588.82 | Assumption |
|---|---|---|
| 10% instant discount | ₹5,888.20 | Entire eligible amount discounted; sufficient cap |
| 5% cashback | ₹11,800 | Completed ₹100 blocks give ₹590 cashback |
| 1% cashback | ₹58,900 across sufficient billing cycles | Completed ₹100 blocks give ₹589; ₹500 cycle cap means this cannot all earn in one cycle |
This is gross fee recovery. If your alternative already earns 5% on a 10% category, the improvement is five percentage points. Recovering the illustrated fee from that difference alone requires approximately ₹11,776.40 of qualifying purchases, before other restrictions.
SBI Card confirms renewal-fee reversal on ₹2 lakh annual spending. Check the qualifying-spend rules. Moving purchases from a better card merely to save ₹588.82 can leave you worse off.
Gold, Movies and Fuel: Value Them When You Use Them
| Extra | Confirmed benefit | How to value it |
|---|---|---|
| Zomato Gold | Six months on card activation | Use your avoided membership cost, not an invented face value |
| District movie BOGO | Once per month per cardholder; two tickets in one transaction; up to ₹200 off the second | Two ₹350 tickets could cost ₹500 before other charges if the full ₹200 offer applies |
| Fuel surcharge waiver | 1% on ₹500–₹4,000 transactions; ₹200 per statement cycle per account | A qualifying ₹2,000 transaction can waive ₹20 of surcharge, subject to applicable terms |
The movie FAQ does not explicitly settle interaction with the shared Eternal cap or simultaneous use of District’s 10% offer. The worked budgets exclude movie savings. Fuel earns no cashback; a surcharge waiver refunds an eligible charge.
The Rules That Protect the Maths
Automatic cashback is posted within two working days of statement generation. Returns, cancellations and reversals can reduce or reverse it. EMI conversion can reverse cashback too; the booklet has inconsistent reinstatement wording after EMI cancellation, so do not count on restoration.
The official exclusions include fuel, rent, insurance, jewellery, education, utilities, government payments, gaming, wallets, gift/prepaid-card loads, cash advances, fees and charges, and Merchant EMI/Flexipay. The full MCC list is broader than these category names.
Eternal instant-discount purchases do not earn additional card cashback. Baby food/feeding essentials and tobacco/Paan Corner items on Eternal apps are also listed among cashback exclusions; that alone does not establish their instant-discount treatment.
Check actual checkout rules for minimum orders, individual-offer limits, mixed baskets and coupon compatibility. The calculations assume no extra coupon stacking, no interest or late fees, and full payment on time.
The Book1A Take: Give the Card a Clear Job
Our Friday shopper does not need a ₹42,000 target to make the card useful. On a ₹20,000 monthly budget, the illustration produces ₹1,060 in benefits. On ₹5,000 of Zomato and Blinkit purchases, it produces ₹350.
The stronger decision comes after checking the existing wallet. In one comparison, an apparently generous ₹4,200 annual benefit becomes just ₹611.18 of extra value after the illustrated fee. In another, keeping a second card for weaker categories improves the outcome.
| Your situation | Our reading |
|---|---|
| Regular Zomato, Blinkit and District use | A strong reason to evaluate Eternal against existing cards |
| Most purchases qualify for the 10% categories | Potentially better return per rupee |
| Mostly small merchant UPI payments | Calculate rounding before relying on the 1% headline |
| Existing cards already cover the same platforms well | Count additional value after the new fee |
| Little use of Eternal platforms | The core proposition may have limited relevance |
| Extra spending needed to reach caps or waiver | Keep the original budget; reconsider the card’s role |
Use Eternal where it improves the bill. Keep track of the cap. Let the better card handle the rest.
That is how a modest-fee card earns a place in a wallet: one useful purchase at a time.
Make the Whole Wallet Work with Book1A
The next decision is rarely just “Which card is best?” It is which card belongs on each expense, which cap remains available and which milestone is worth pursuing.
The Book1A dashboard helps bring cards, points, miles and vouchers into one place. For a personalised strategy around spending and travel, explore Book1A membership options.
Continue reading our SBI Cashback review and guide to everyday return on spending.
Examples are hypothetical, not personal spending claims or promised returns. Rates and conditions were checked against SBI Card’s official terms on 15 October 2026. Annual calculations assume repeated eligible purchases and unchanged terms; actual billing periods, taxes, rounding and eligibility decide the outcome. Initial launch screenshots below are historical promotional material; official terms prevail.
Initial Promotional Screens
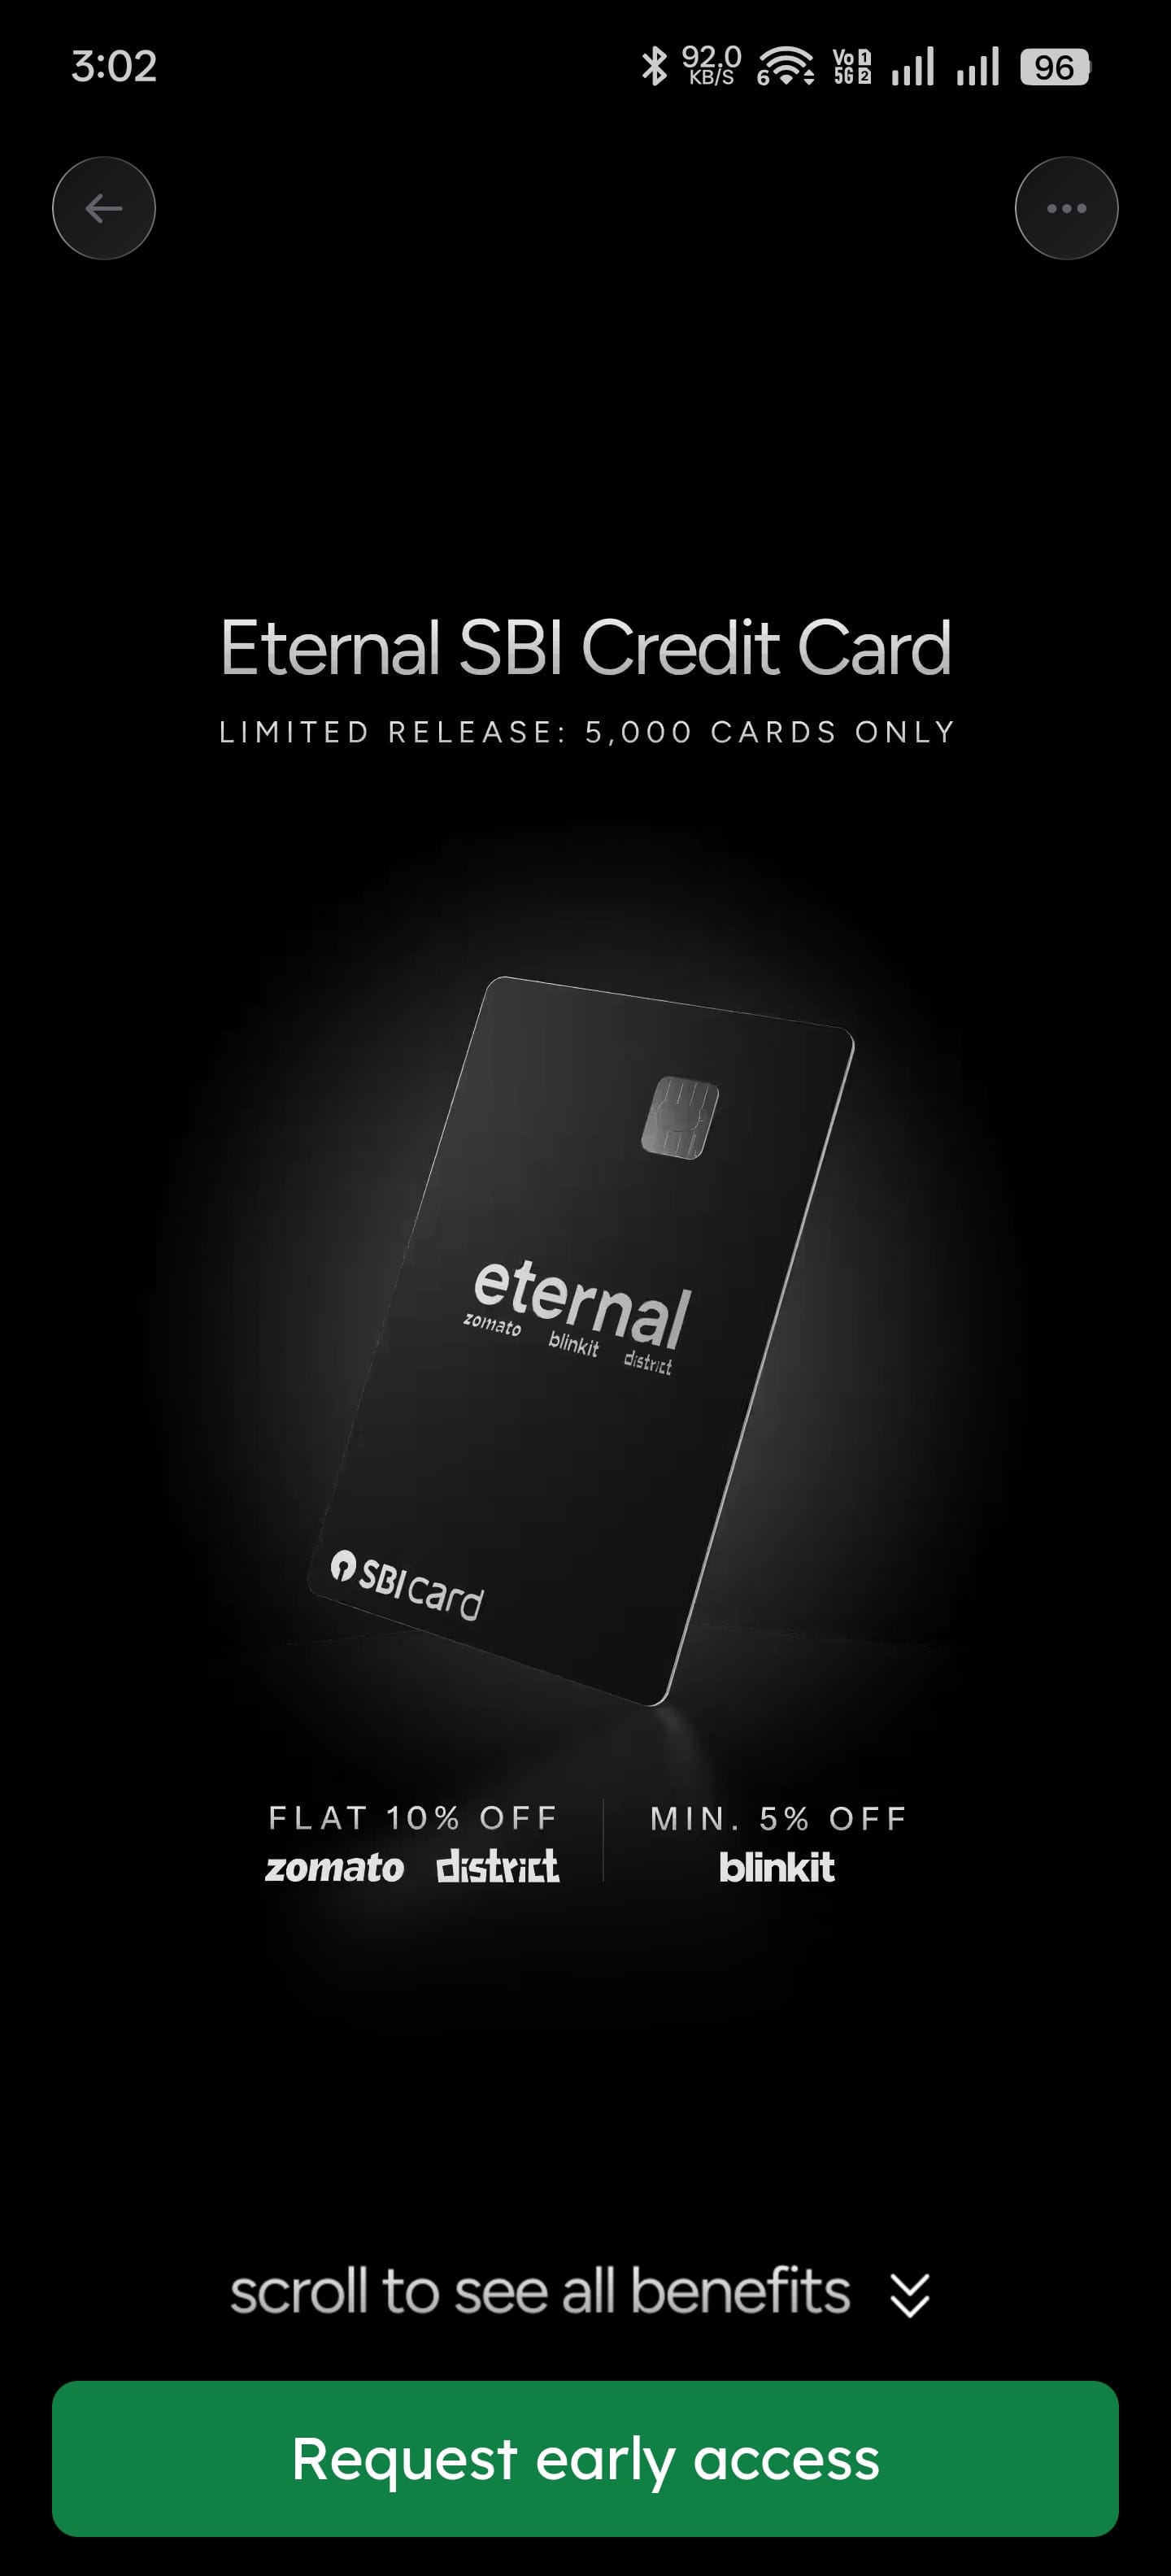
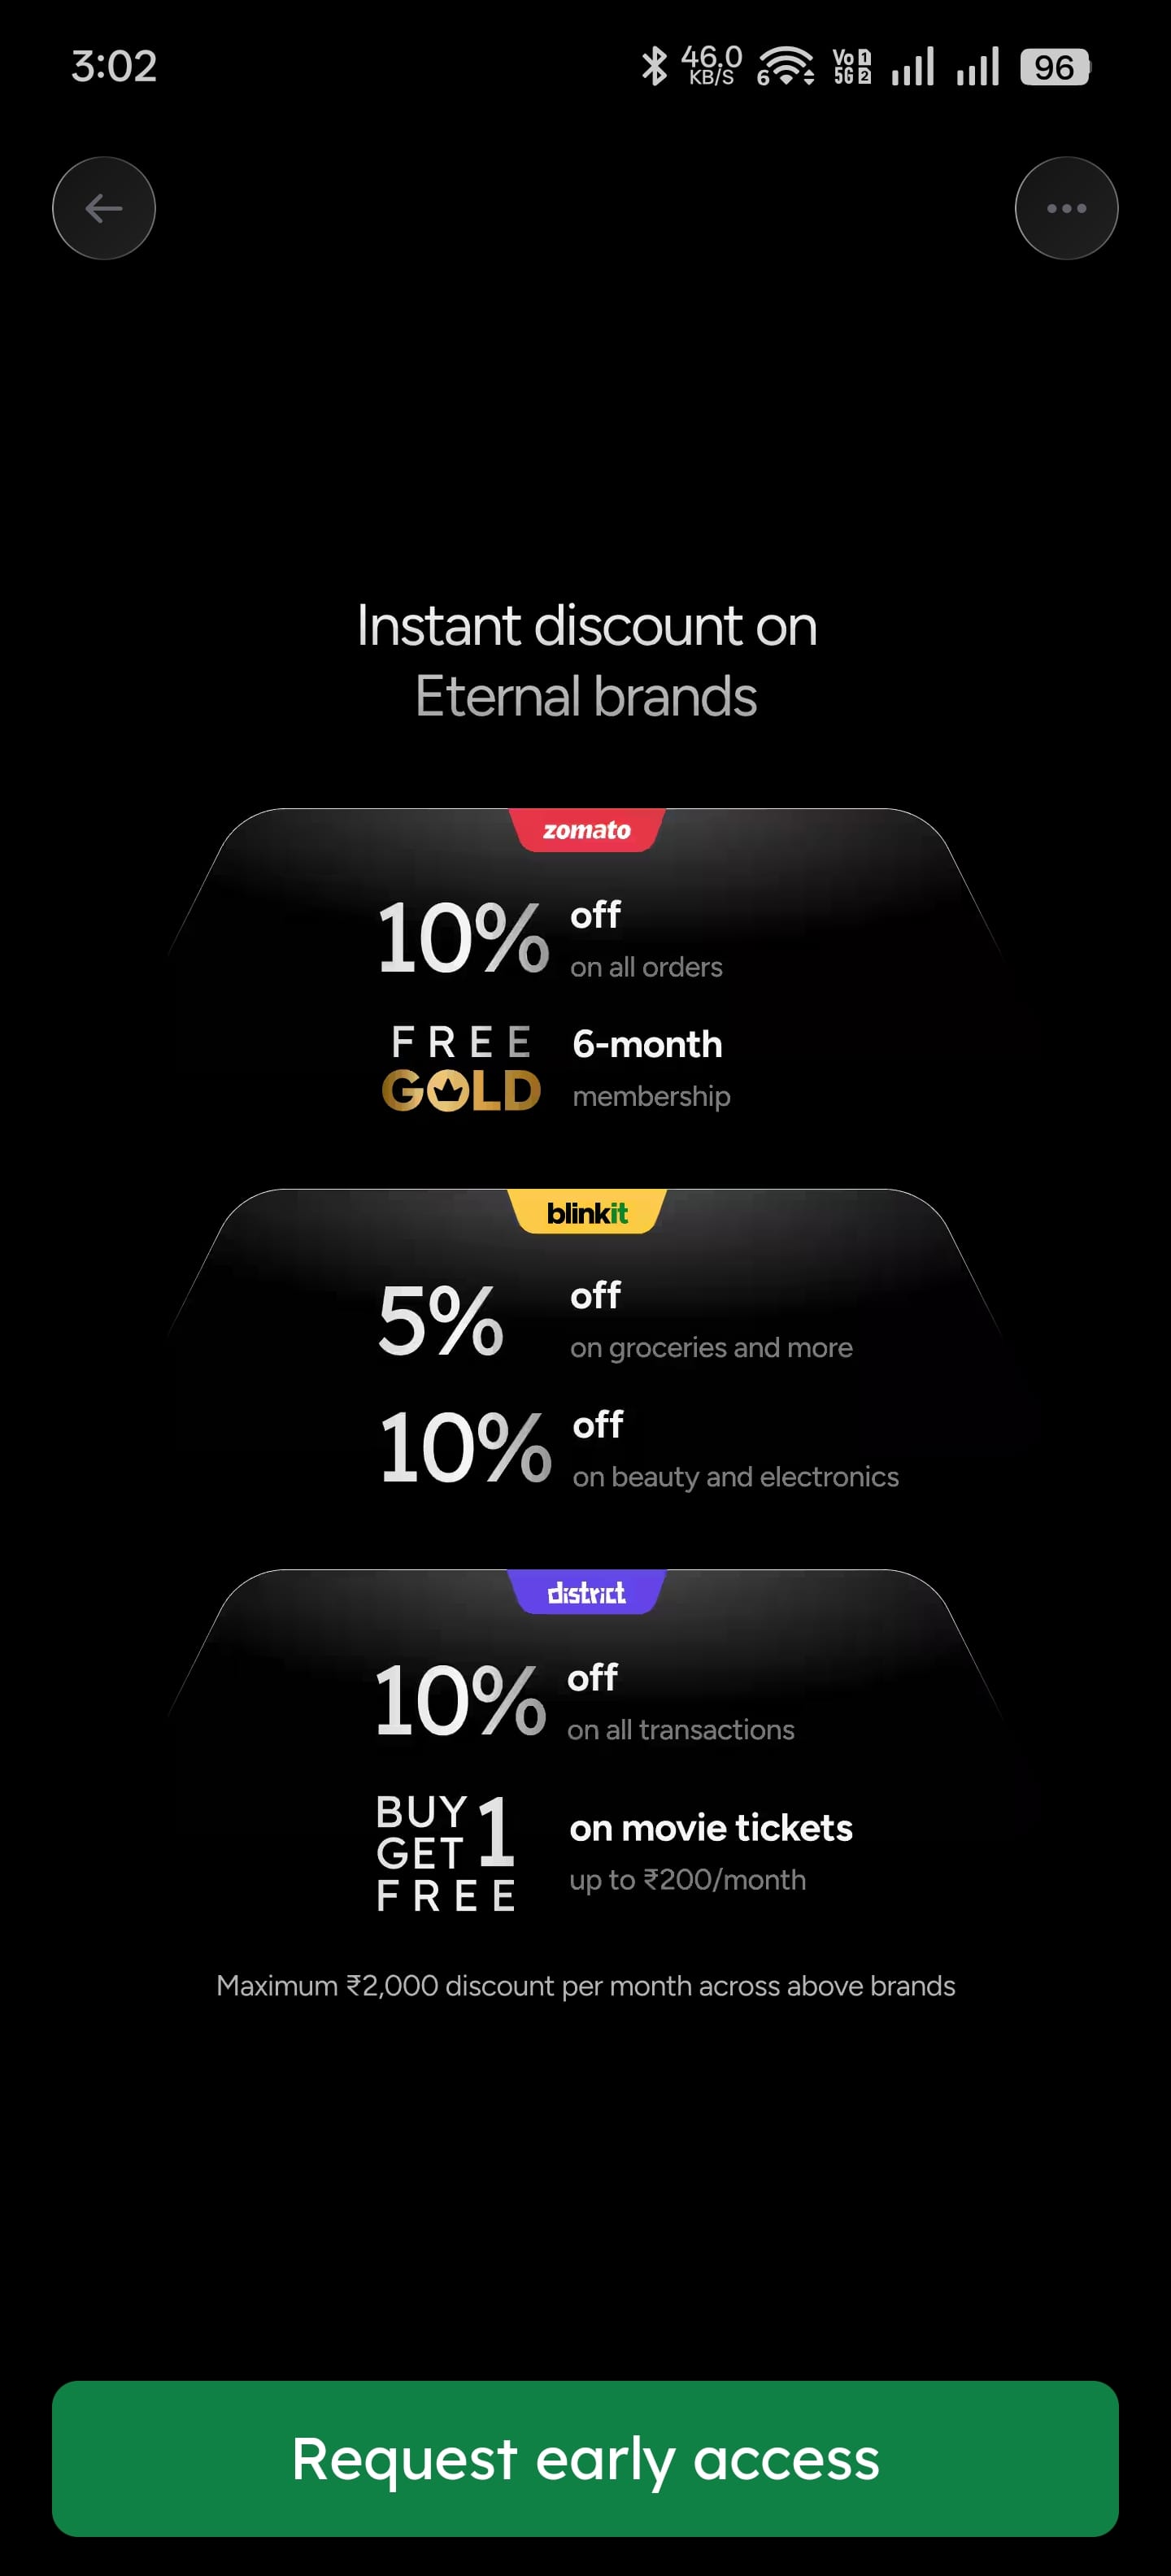
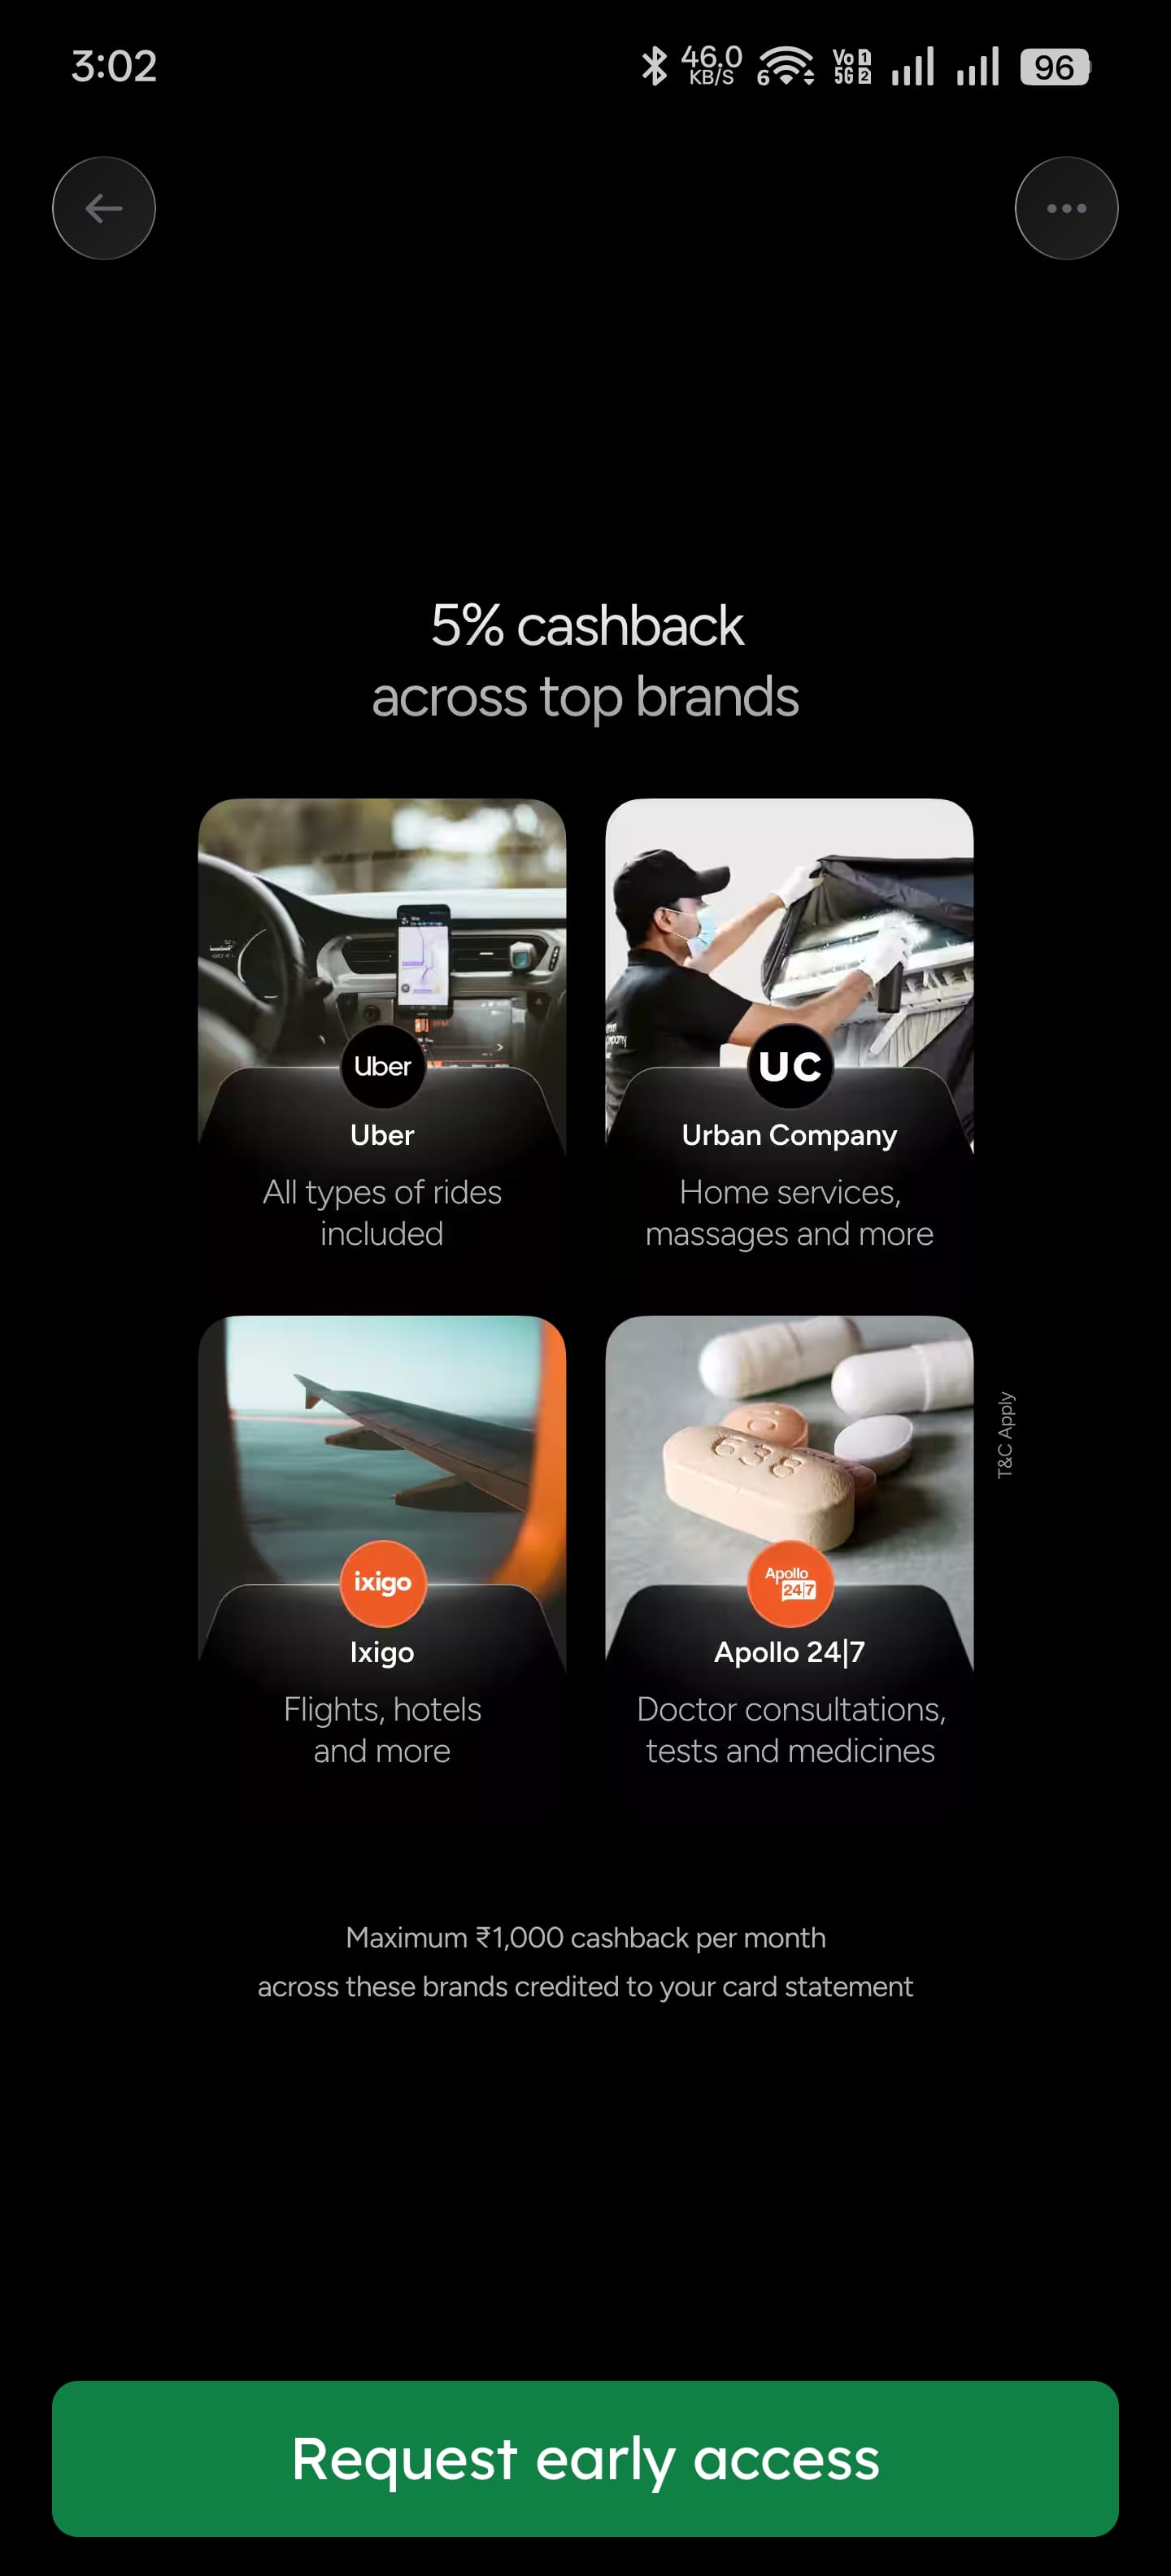
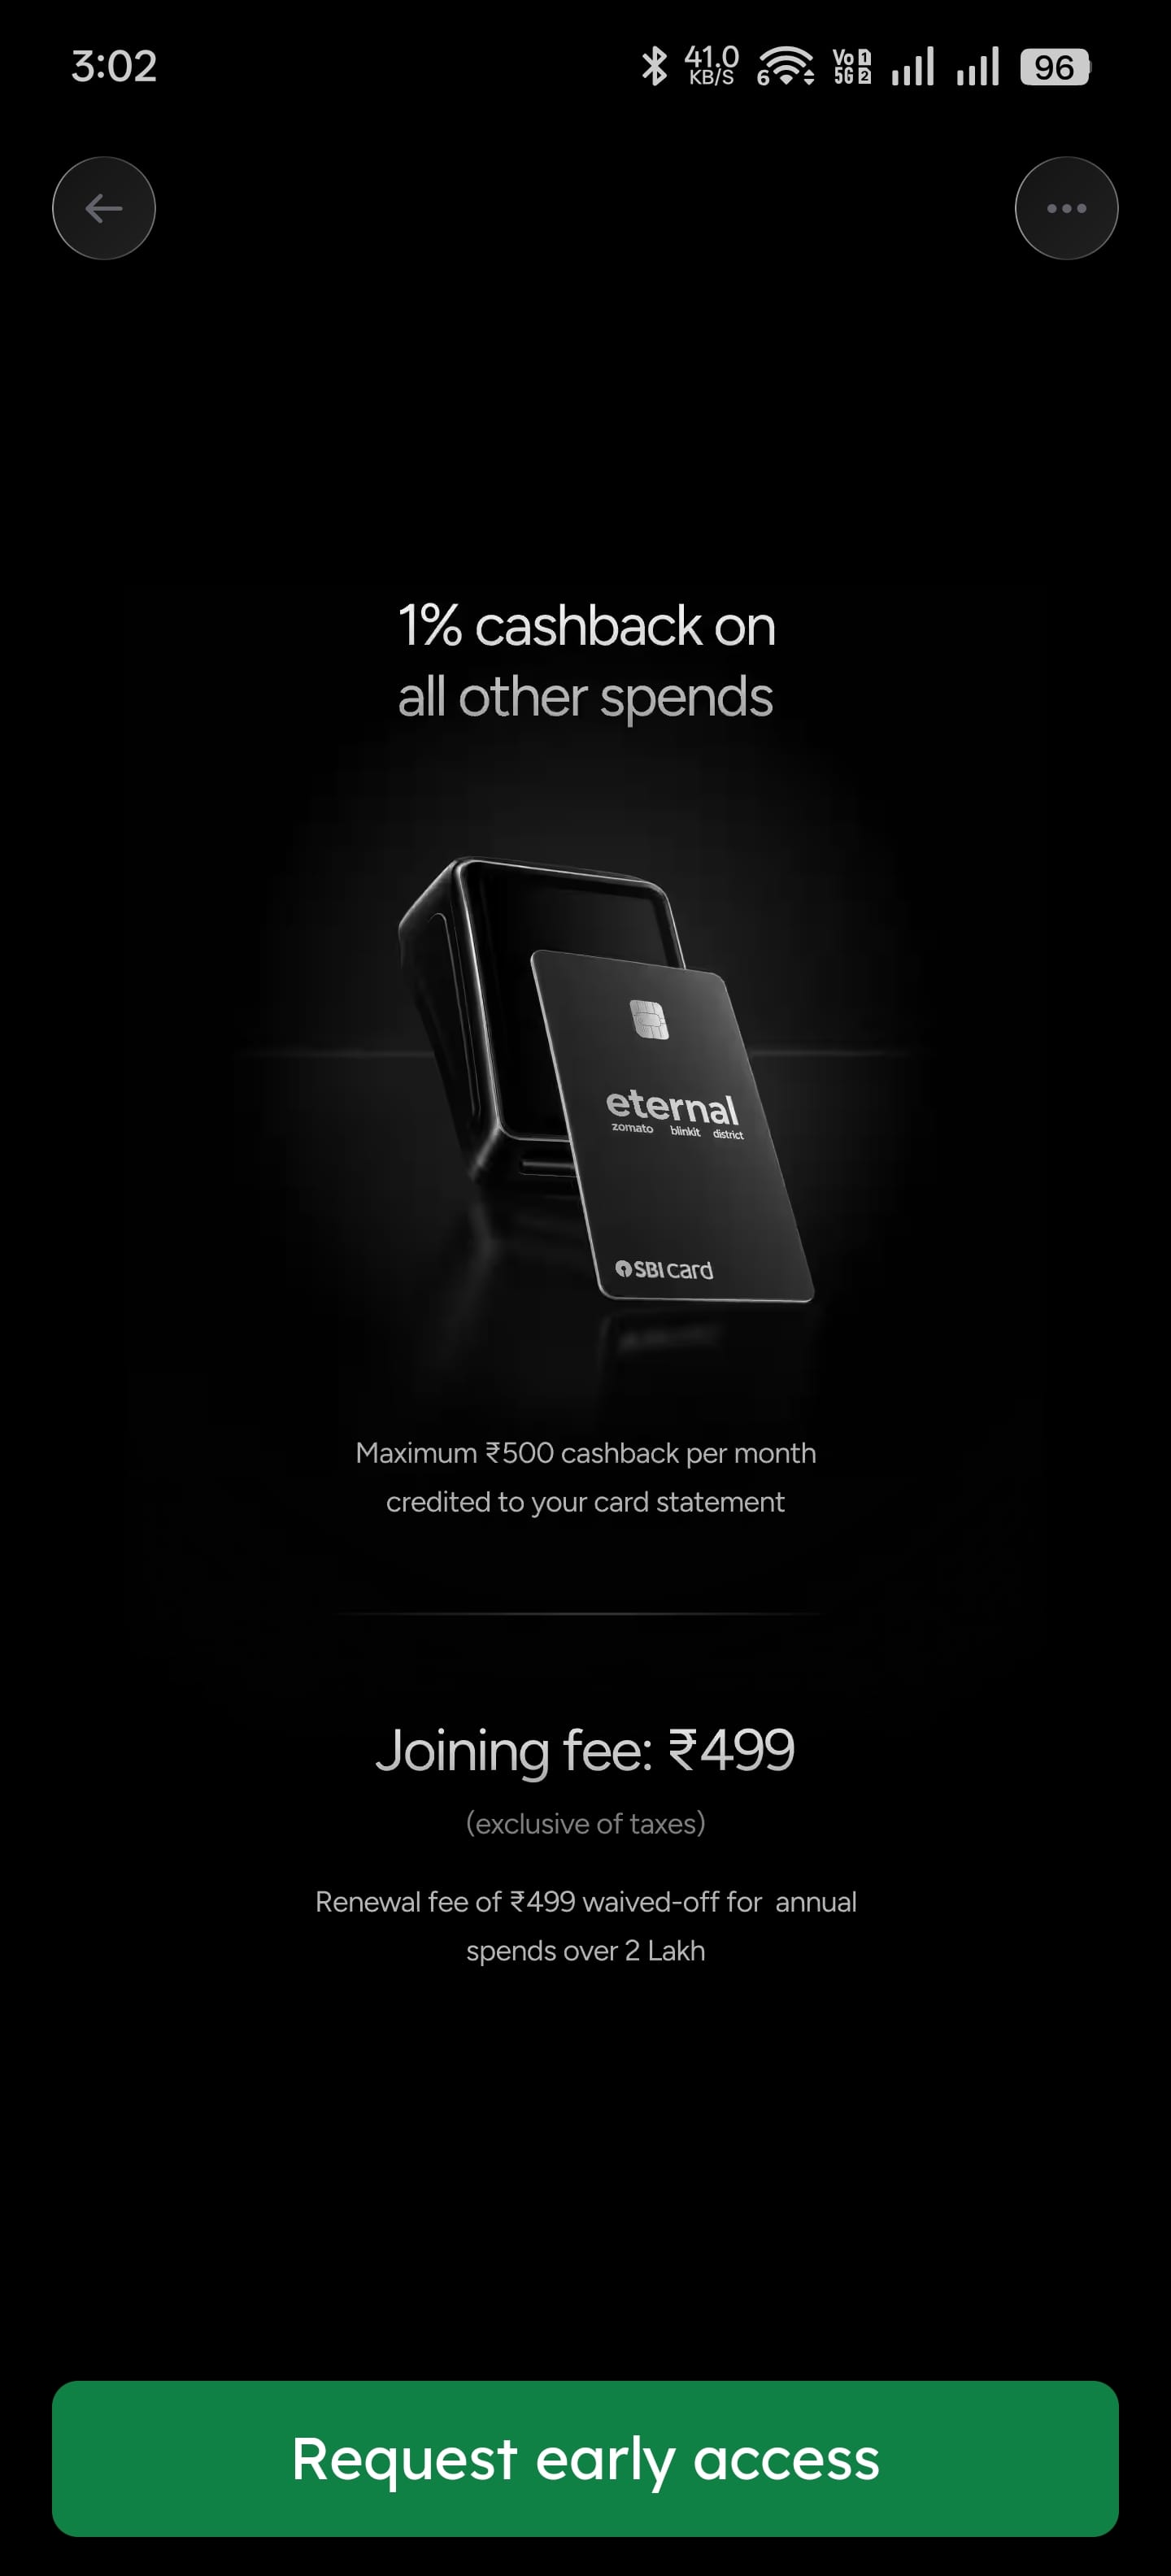
Initial promotional screens. For ixigo, billing-cycle caps and the fee-waiver threshold, use the official terms explained above.